Property Empire Mortgages & Loans Guide
Use leverage to grow net worth without letting Stress and interest erase your rent roll.
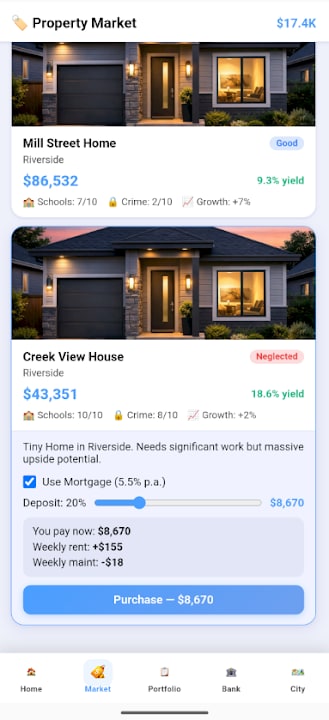
Mortgages and loans are how Property Empire turns a small Riverside stake into a multi-district portfolio—and how careless landlords go broke in three weeks. This guide explains when to borrow, how to size payments against rental yield, how Stress interacts with debt, and how to unwind bad leverage before you unlock Greenfield Suburbs, Campus Quarter, or Port Industrial.
Why leverage exists in a weekly tycoon
Each week is a turn with limited Energy and finite cash. A mortgage lets you control a property whose equity upside (appreciation after renovation, or capitalized rent) exceeds the interest and Stress cost of the loan. Used well, debt accelerates the climb from Small Landlord toward citywide tycoon. Used poorly, debt forces fire sales of Poor repairs you meant to finish and tanks Happiness when you underfund tenants.
Property Empire is single-player: single-player only partner will cover your payment. Plan as if every week’s rent must clear mortgage service plus a buffer.
Mortgage versus short loan mindset
Think of a mortgage as long attachment to a hold or value-add unit: you expect many rent ticks or a planned flip exit. Think of a loan as bridge cash for renovation materials, a temporary vacancy, or a deposit toward the next district unlock. Bridge debt should die quickly after a flip closes or a Campus Quarter lease fills. Lingering bridge loans on a Neglected shell are how Stress compounds.
Before signing either, open Rental Yield and Mortgage Planner Tips. Rough rule: projected weekly net rent should comfortably exceed weekly debt service after realistic vacancy and upkeep—not best-case brochure numbers.
Sizing debt to Energy and renovations
Borrowing enough to buy but not enough to cure Poor or Neglected conditions traps you. Lenders do not renovate for you. Price the full stack:
- Purchase price and closing friction.
- Critical repairs required before rentable or saleable.
- Energy weeks those repairs need.
- Mortgage payment during those offline weeks.
- Stress impact if Energy overtime is required.
If the stack only works when every week is perfect, shrink the loan or pick a cheaper Riverside unit. See Flip & Renovate for sequencing repairs so the property starts earning sooner.
Stress: the hidden interest rate
On-paper interest is not the only cost. High Stress reduces effective capacity: you miss tenant issues, Happiness slides, vacancies appear, and the same mortgage suddenly looks larger. When Stress spikes after a loan draw, prioritize Calm weeks—collect rent, skip speculative bids, maybe concede a small rent adjustment to keep a good tenant. Tenants & Rent covers Happiness triage.
District-aware borrowing
- Riverside — Best classroom for first mortgages. Lower prices, clearer mistakes, working-class rents that still teach payment discipline.
- Greenfield Suburbs — Family demand and school ratings can support stronger rents, but purchase prices rise. Do not carry Riverside-sized reserves into Greenfield-sized loans.
- Campus Quarter — High demand helps fill units, but turnover and seasonal emptiness can interrupt payment coverage. Keep a thicker cash buffer.
- Port Industrial — Commercial upside and growth metrics tempt big leverage; crime and different tenant profiles can disrupt income. Unlock and borrow here only with stable reputation and cash.
Map context: Districts & City Map and Best Districts.
Payment tactics that protect net worth
- Align major renovations so the unit can rent before the first heavy payment week when possible.
- Prefer paying down the highest Stress or highest rate balance when you get flip proceeds or a rare promo gift from the Codes Hub.
- Avoid cross-collateral mental accounting: each property should roughly stand alone.
- Never unlock a new district the same week you max a new mortgage unless cash coverage is boringly safe.
Warning signs you are overborrowed
- Stress stays elevated even on quiet weeks.
- You skip Happiness fixes because Energy is spent chasing new deals.
- You need a second loan to finish the first property’s Neglected repairs.
- Net worth ticks up on paper (property values) while cash and Energy feel worse every week.
If three of those fire, sell or refinance strategy: complete the cheapest path to a marketable unit, exit, clear debt, then rebuild. Best Properties helps you spot which holds deserve patience versus which should be cut.
Reputation and clean books
Solvent mortgage weeks and finished projects feed landlord reputation. Constant arrears vibes do not. Climb ranks with disciplined leverage—see Landlord Reputation Ranks and the Players Hub.
Practical week template
- List all payments due this week.
- Forecast rent collected and known vacancies.
- Reserve Energy for any repair that unlocks rent on a mortgaged unit.
- Only then consider a new loan for a new buy.
- End week with a written note (mental is fine) on Stress trend.
New players should finish Getting Started before complex multi-loan stacks. Patch and bug context—including player reports about buildings sometimes not completing—lives on Version History. Official help: potatoface995@gmail.com via the Links Hub.
Leverage is a tool, not a personality. Property Empire rewards landlords who borrow on purpose, renovate on schedule, and keep Happiness high enough that rent never becomes a prayer.
Frequently Asked Questions
Quick answers to the most common questions.
When should I take my first mortgage?
After you understand Riverside rents and renovation Energy costs—usually once a simple hold or flip plan clearly covers payments with a buffer.
What is the biggest mortgage mistake?
Borrowing to buy without budgeting repairs, vacancy, and Stress. Distressed Poor/Neglected stock needs cure capital, not just purchase capital.
Should I use loans to unlock districts faster?
Only if existing payments stay comfortable. Unlocking Greenfield, Campus, or Port Industrial while maxed on debt often multiplies problems.
How does debt affect Stress?
Heavy payments and tight cash raise Stress, which reduces how effectively you spend Energy and can cascade into Happiness issues.
Where can I plan numbers in more detail?
Use the Mortgage Planner Tips and Rental Yield pages under Tools, then verify district metrics on the districts guide.